One platform from the first tap to the last instalment.
Amanova runs retail and SME lending end to end: a customer app on any phone, checks that run before anyone opens the file, decisions with reasons, compliance gates, disbursement, servicing and collections. Staff work in a modern workspace; administrators set up products and rules in the classic desk.
Customers apply from any phone.
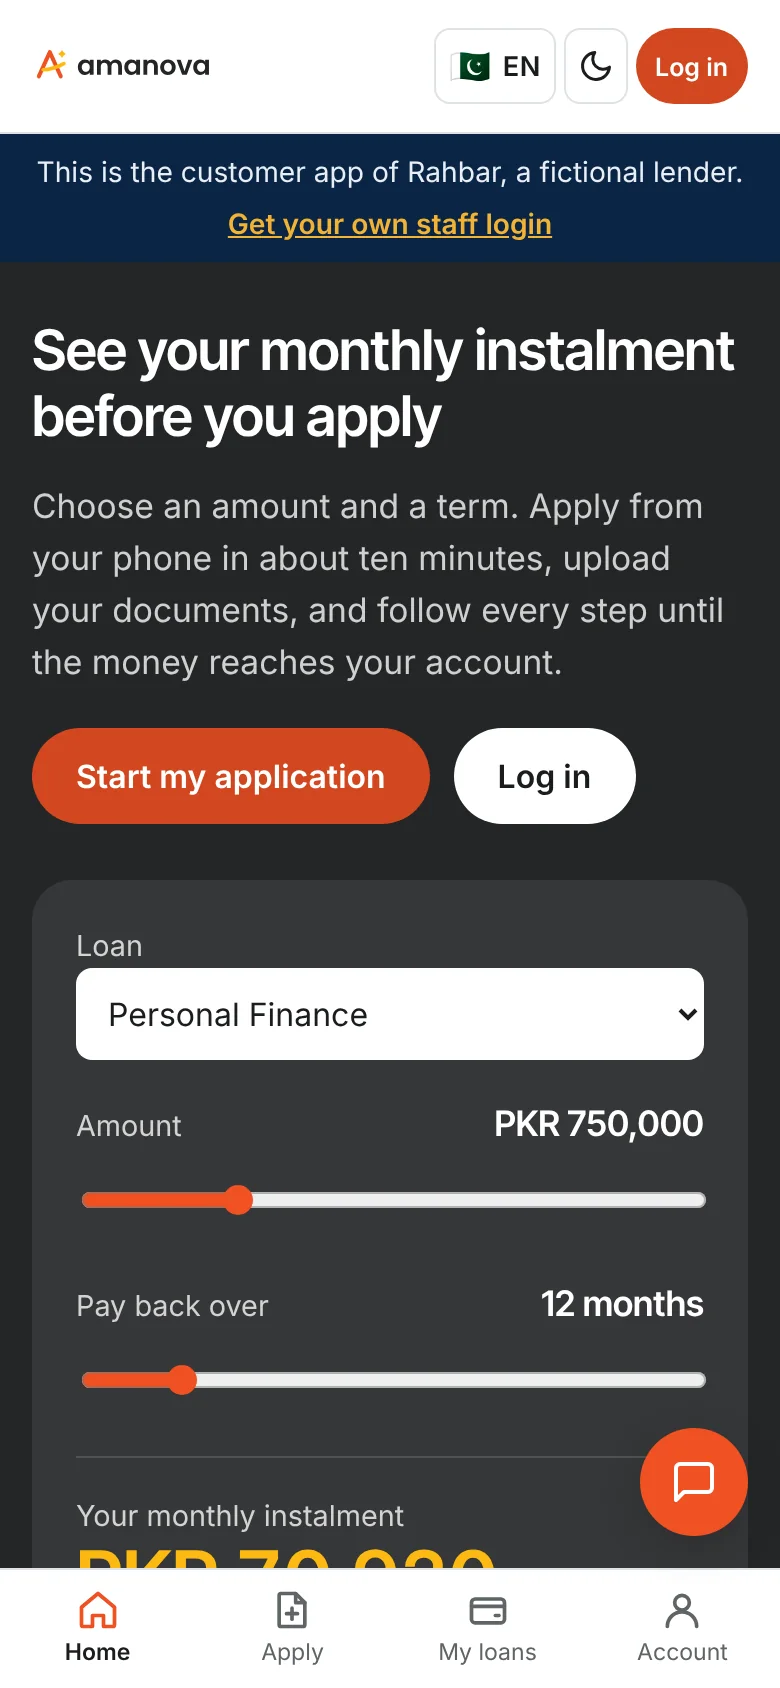
- Sign up with the national ID, a mobile number and a one-time code. No branch visit.
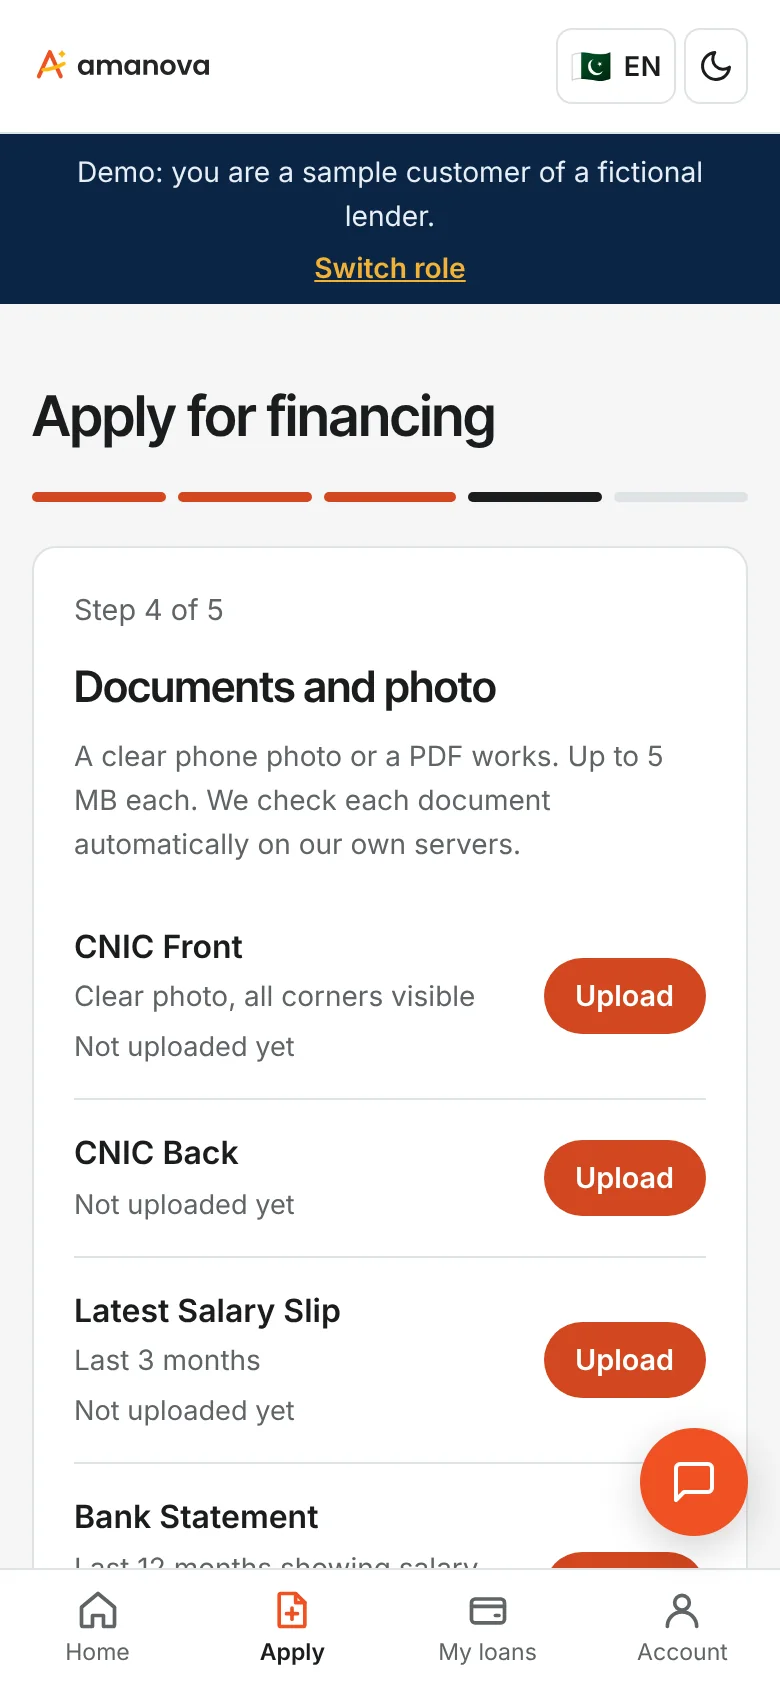
- See the instalment before applying, then upload documents and a live photo, one step at a time.
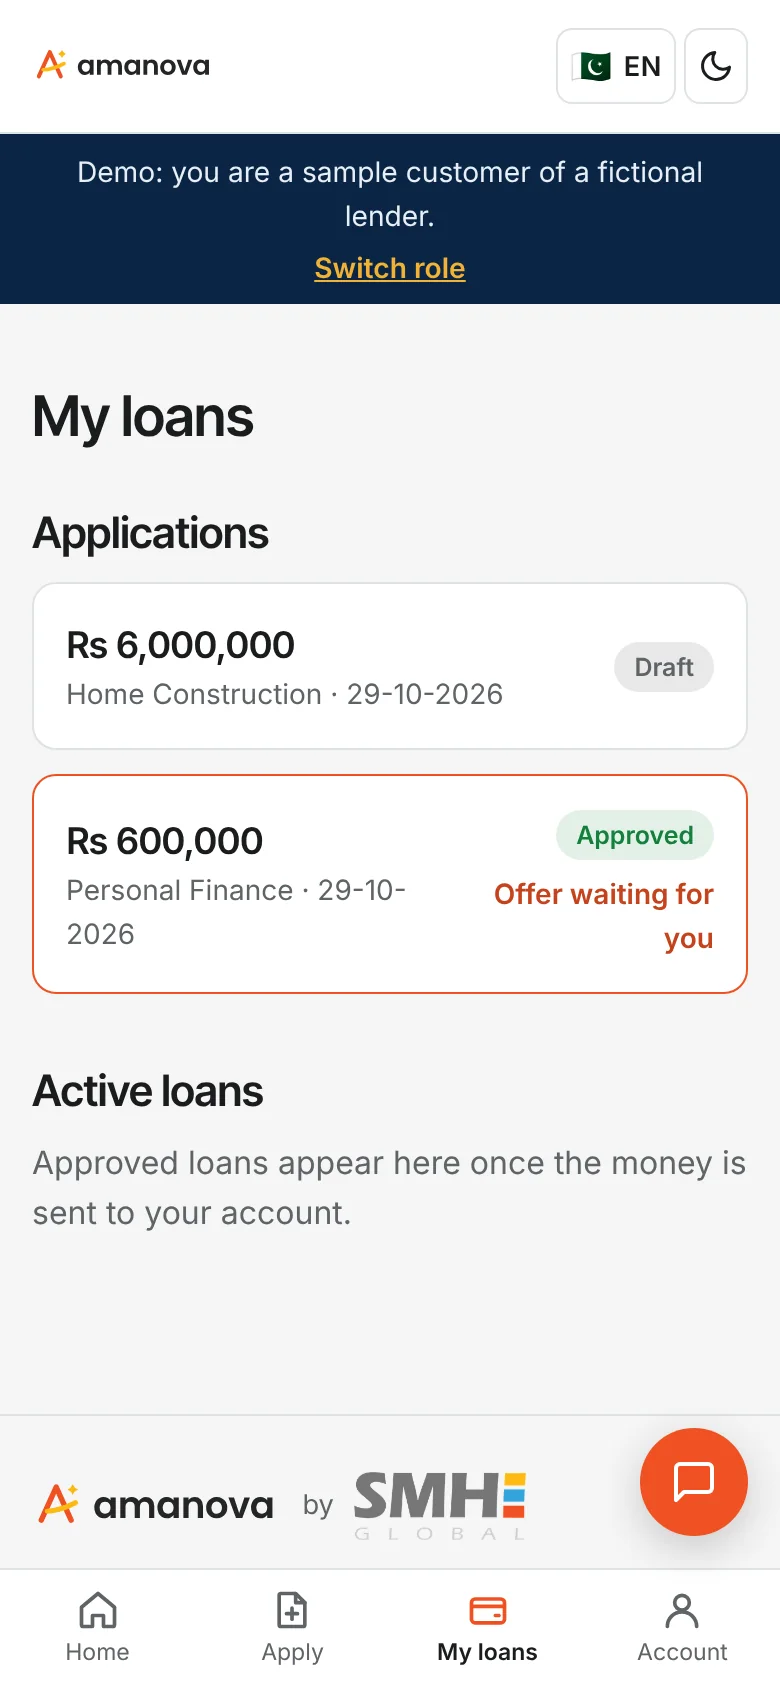
- Follow the application, read the Key Fact Statement and accept the offer on the phone.
- Use the web, the installable app, WhatsApp, or USSD on a feature phone.
- Eight languages, with right-to-left screens for Urdu and Arabic.
Checks run before anyone opens the file.
- The national ID is checked with the country's identity service: NADRA, Nafath, UAE Pass, NIMC and others.
- Document AI reads ID cards, salary slips and bank statements, and compares them with what the customer entered.
- Affordability is measured against your debt burden limit.
- Credit bureau reports are pulled through the bureau connector, or uploaded and read: eCIB, SIMAH, AECB, CRC and others.
- Every applicant gets a KYC risk rating and sanctions screening.
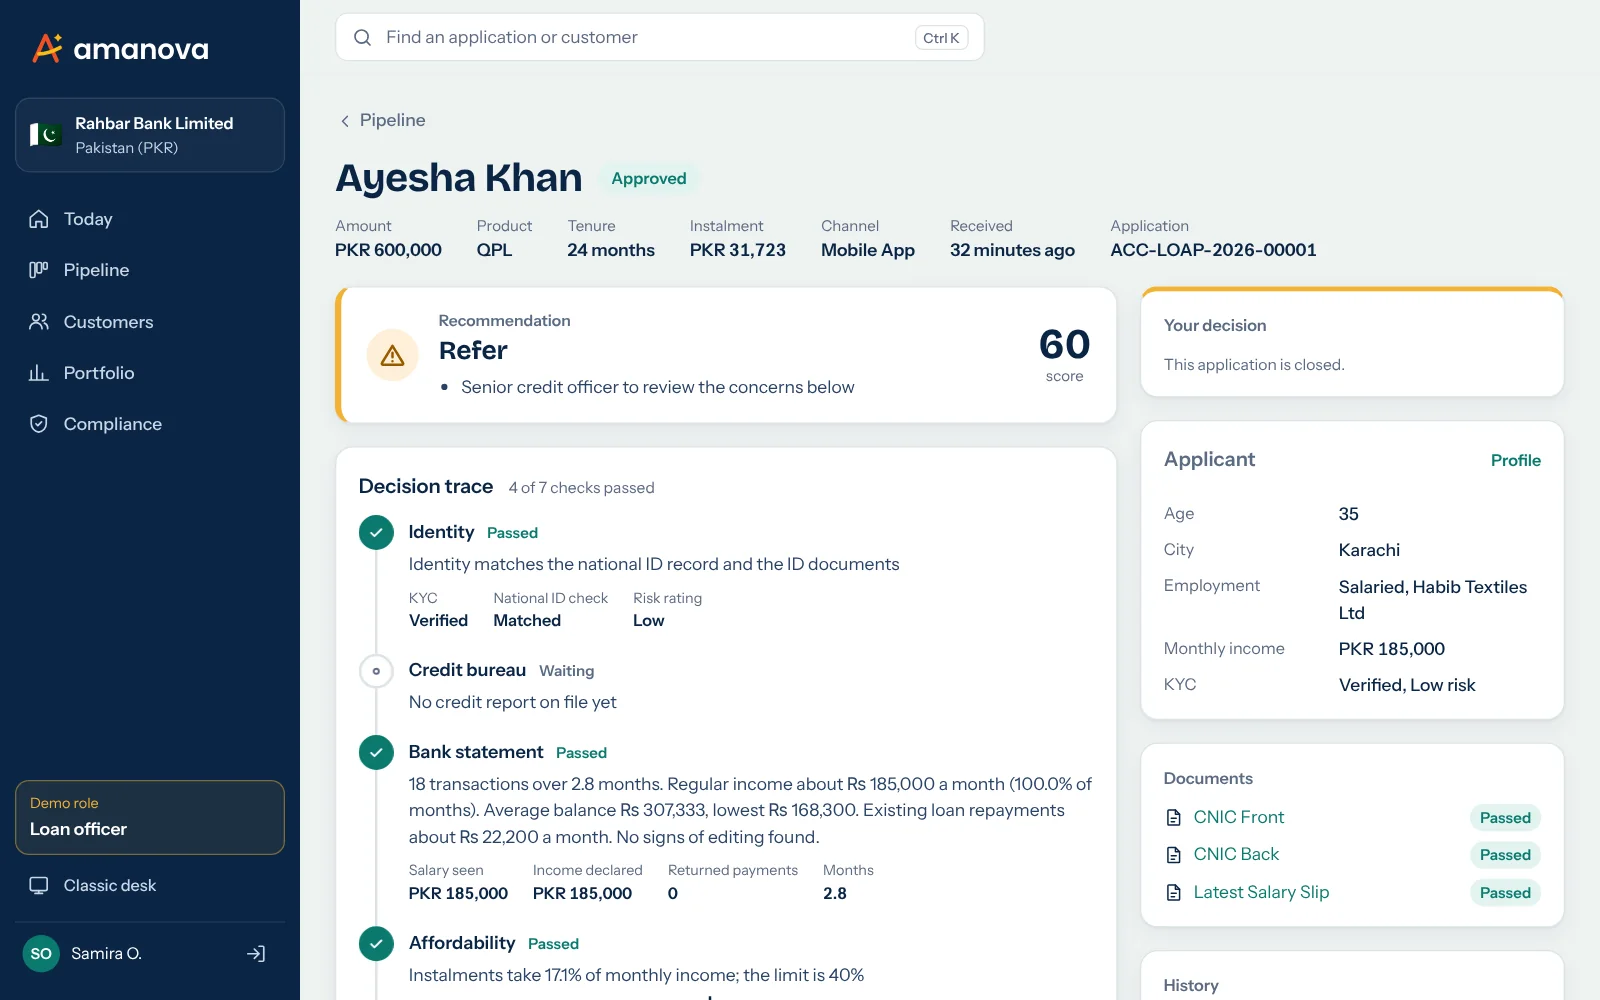
Every decision comes with its reasons.
- A seven-step decision trace: identity, credit bureau, bank statement, affordability, fraud, compliance and score.
- Scorecards and policy rules give a recommendation the underwriter can follow or overrule.
- The AI drafts the credit memo. A person decides, and asking for information or declining needs a written note.
- Declined customers are told what helped, what held them back and what they can do next.
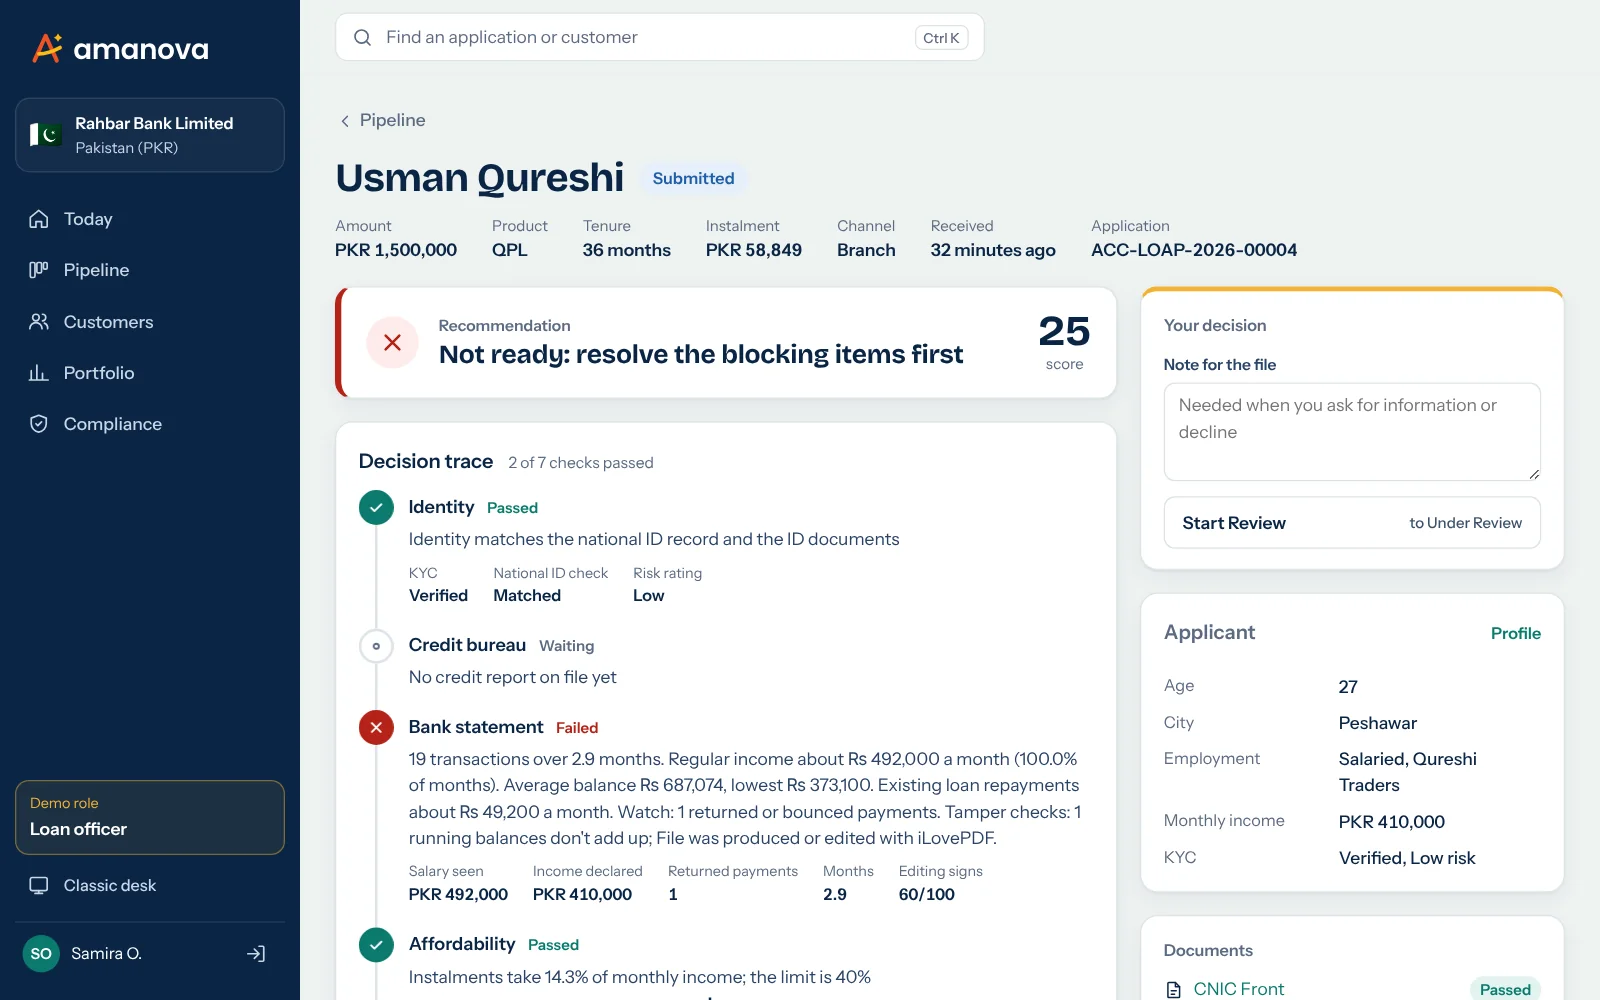
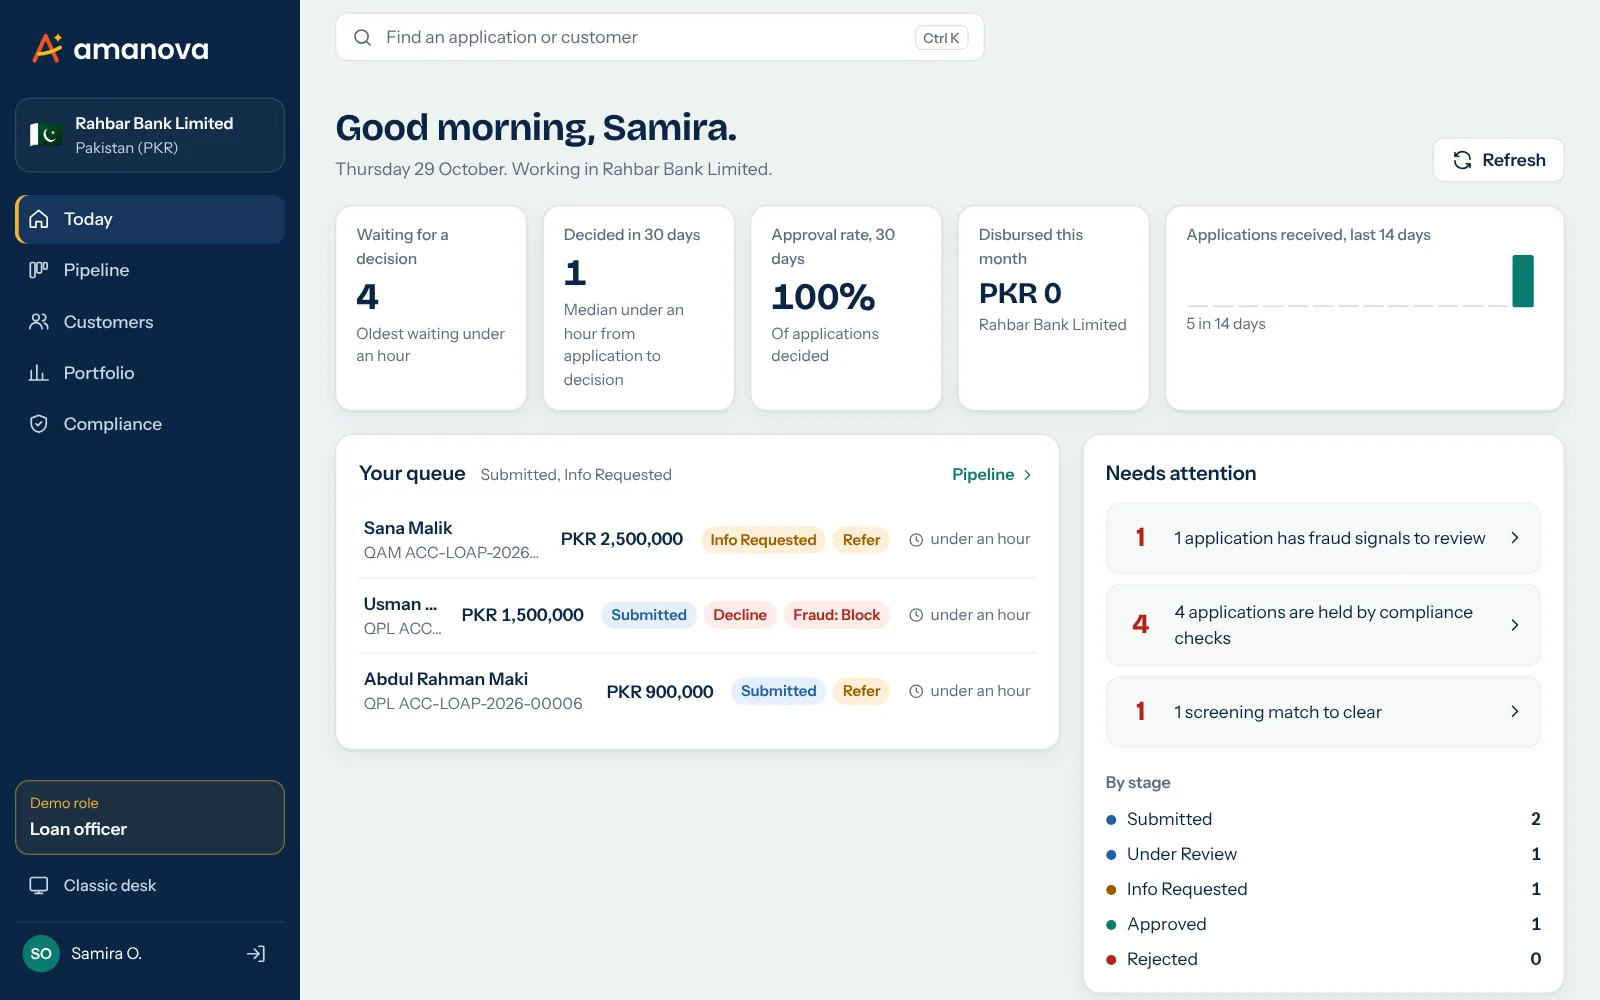
A workspace for every role.
- Today shows what is waiting, how fast decisions are made and what needs attention.
- Queues for the loan officer, underwriter, credit manager and compliance officer.
- Only the next steps the workflow allows are offered, and every step is logged.
- Search everything with Ctrl K, in light or dark mode, on a laptop or a phone.
- Product and rule set-up stays in the classic desk, one click away.
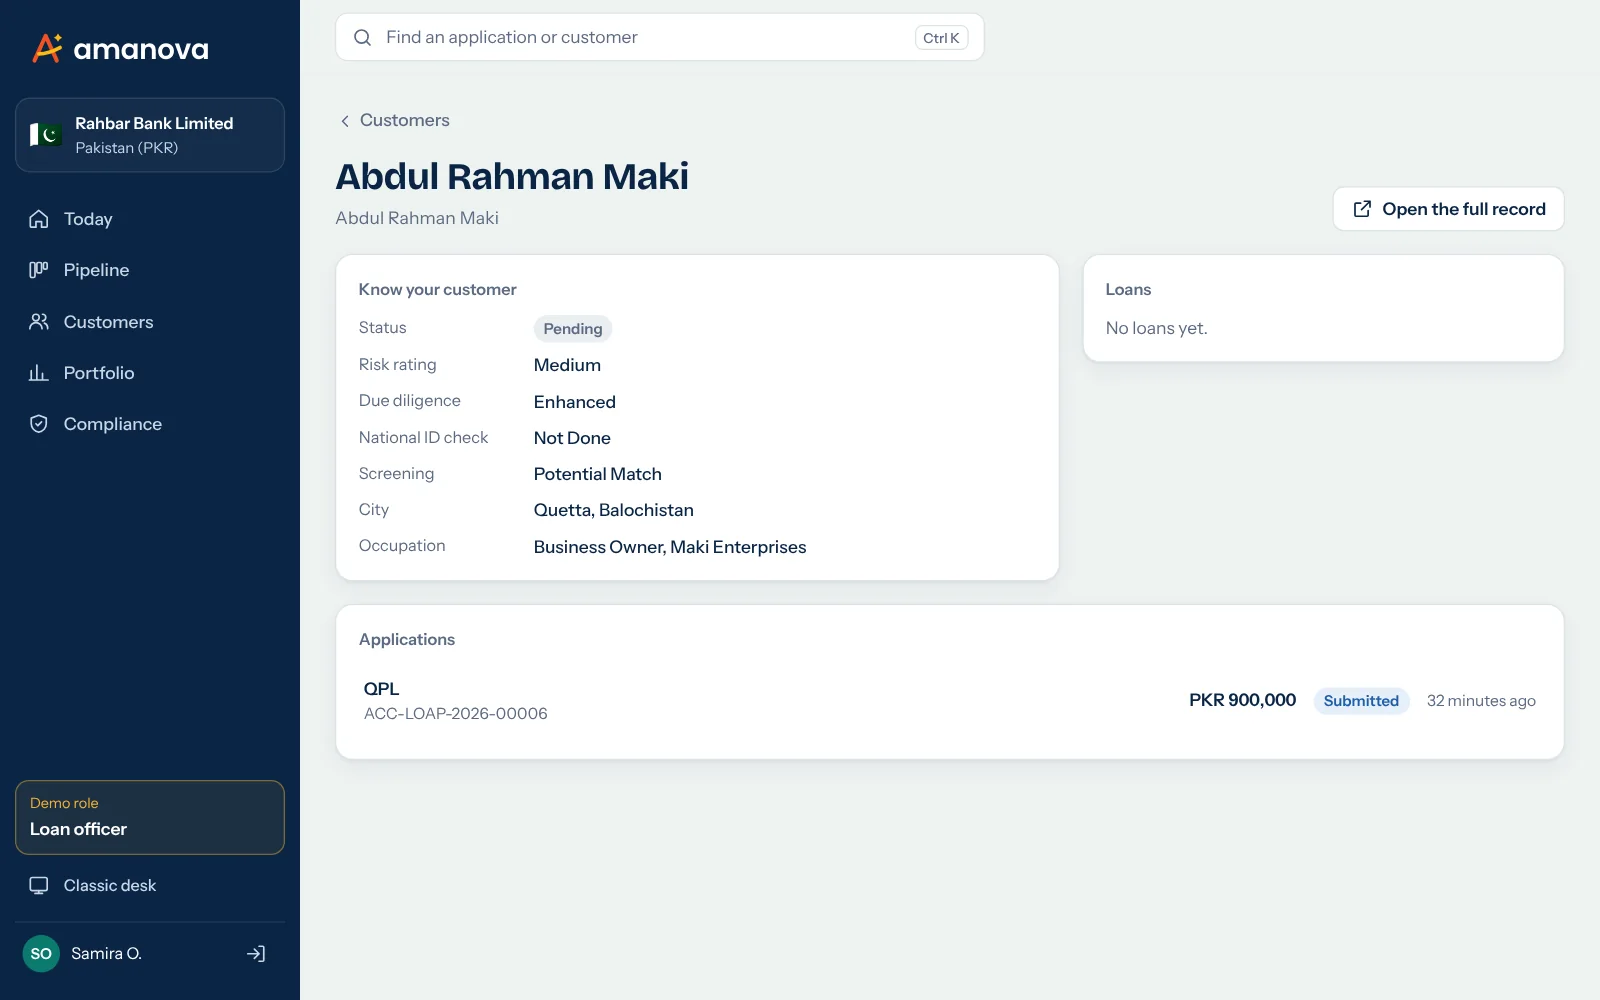
One view of each customer.
- KYC status, risk rating and due diligence level.
- National ID check and screening result.
- Every application and loan, in the entity where the customer banks.
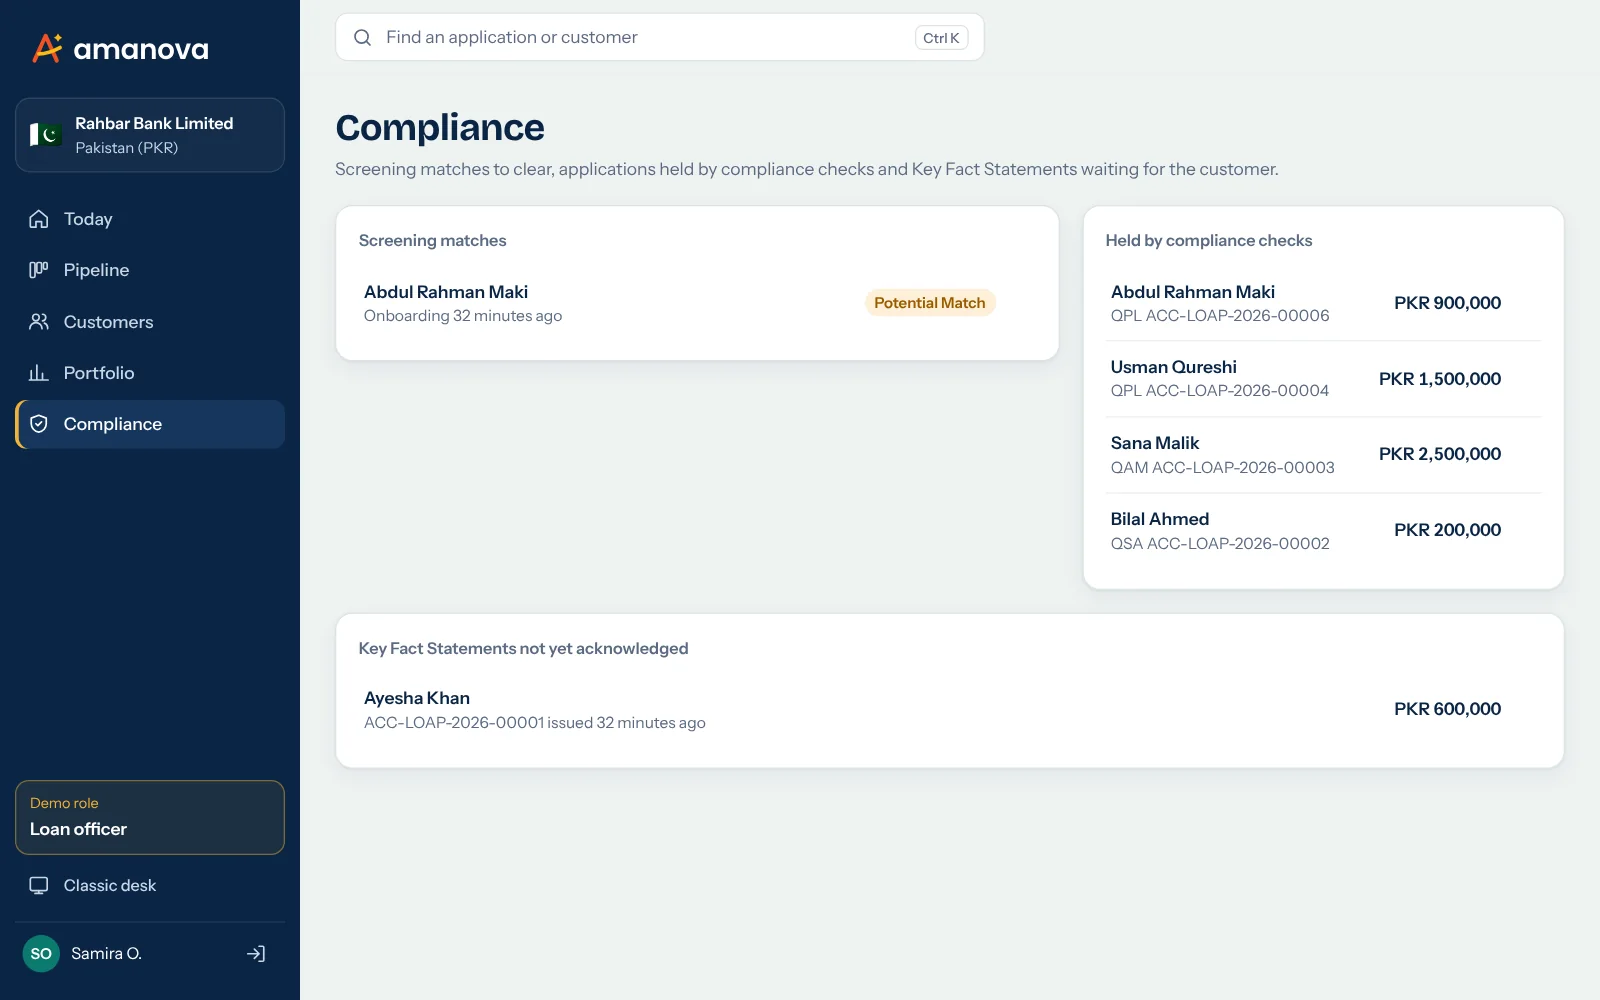
Compliance is part of the workflow.
Gates stop an approval until the checks are done.
- KYC, PEP and sanctions screening with periodic review.
- Credit bureau reporting files and enquiries.
- Key Fact Statements, APR and cooling-off periods.
- Suspicious and cash transaction reports.
- Consent records, and data kept in your country.
- A full audit trail for every decision and AI result.
After approval, the same system carries on.
Disburse
The Key Fact Statement in the customer's language, acceptance with a one-time code, and posting to your core banking system through the API.
Service
Repayment schedules, profit or interest accrual, repayments, early settlement, rescheduling and loan classification.
Collect
Early warning scores every active loan each night and suggests the next action, the channel and a polite message within the conduct rules.
Islamic and conventional products, side by side.
Personal, salary-backed, SME and gold-backed finance, with Murabaha, Ijarah, Diminishing Musharakah and Tawarruq for Islamic products. Each product carries its own limits, pricing, documents and disclosures for each country.
See it with your own products
We'll set up the demo with your products, your limits and your brand, then walk your credit, compliance and IT teams through it.